Author: caian@ineedsurgery.com

  • Day 1: I-SEM goes live

    Day 1: I-SEM goes live

    The I-SEM successfully launched yesterday with the first day-ahead hourly auction and intra-day auction. Day-ahead prices out-turned at a baseload price of €82/MWh, this appeared relatively high considering a day-ahead wind forecast of greater than 2GW for the evening peak  (for comparison the last week of available SEM prices with similar availability profile and less wind generation had a baseload average of €73/MWh).

    The main driver of prices relate to recent forced outages of the three Moneypoint units and a Kilroot unit (~1 GW of in-merit coal generation) and a scheduled outage at Great Island CCGT (400 MW). The equivalent GB baseload price was €75/MWh resulting in a predominant import flow on both EWIC and Moyle interconnectors, both interconnectors flipped to export for the evening peak corresponding with a high wind penetration in I-SEM.
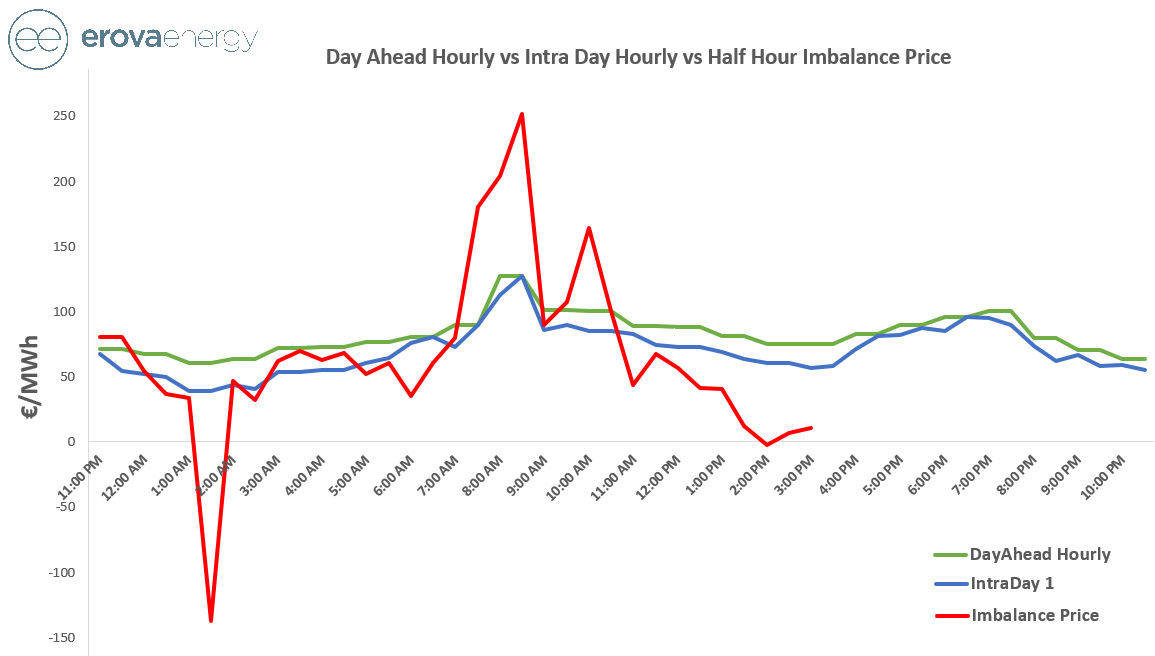
    In terms of liquidity, 75 GWhs traded in day-ahead hourly auction with 10% of this volume traded in the first intra-day auction. Interestingly, the baseload price fell from €82/MWh to €70/MWh between auctions, perhaps related to thinner volumes in the intra-day auction. The intra-day 2 auction (11AM – 11PM) showed a further decline in prices by €3 for the equivalent periods to intra-day 1. Liquidity fears in for the continuous M7 market have been realised with very thin volumes traded across the day (low double digit volumes MW traded in each half hour), these sub-optimal liquidity conditions place increasing pressure on the participants to be balanced after the intra-day auctions.

    The balancing market has proved incredibly volatile with 5 minute imbalance prices ranging from -€1,000/MWh (yes minus one thousand euro!) at 01.55 to +€381/MWh at 08.55 this morning. As anticipated, the wind delta versus forecasted wind is the main factor impacting the long / short direction of the market. Bizarrely, the -€1000/MWh price actually occurred during a short imbalance period.  As is evident from the graph above, wind over-delivering versus forecast results in a very long market across the afternoon and was reflected in the imbalance price.

    Whilst all of this was taking place, Erova announced it’s first Imbalance Management agreement with Greencoat (click here). We provide forcasting and balancing management with I-SEM, removing the exposure to such prices as seen today. To find out further details please contact our Origination Team (contact us).


  • Erova Energy hosted it’s first golf invitational tournament

    Erova Energy hosted it’s first golf invitational tournament

    Friday 13th July

    On Thursday the 12th of July Erova Energy hosted it’s first golf invitational tournament. The event took place at the Portmarnock Hotel and Golf Links in North County Dublin.

    The weather was exceptional and after a prolonged period of drought the course had developed a character seldom seen on Irish links courses, as can be evidenced in the photos. Competition was fierce and everyone enjoyed the unique challenges posed by the course. We had an excellent day and look forward to doing it again.

    Erova were joined by industry participants such as AIB, NTRplc, Greencoat Renewables, Poe, Kiely, Hogan, Lanigan Solicitors, Bank of Ireland, CGNEE, Mason Hayes and Curran Solicitors, Barclays Bank, Low Carbon Investments, O’Carroll Consulting, McCann Fitzgerald Solicitors, TV3, Cornwall Insights, SDLC Investment Banking, Grant Thornton, the Fsrmers Journal and the ESB.

    Thanks to all for coming and feel free to subscribe to our mailing list to be kept posted on next years tournament.

  • I-SEM delayed until October 2018

    I-SEM delayed until October 2018

    The SEMC was left with little alternative after the Market Trial was beset with technical problems and the feedback from various market readiness assessments. The original I-SEM go-live date was 1 October 2017 and this was initially pushed back to 23 May 2018, in March the SEMC warned market participants that this date was now ‘at risk’ due to recurring issues with the central market IT system. On 12 April, The Electricity Association of Ireland (EAI) requested a delay to allow at least two months of “clean” trials before go-live and requested any such date should not coincide with the summer holiday period. Considering these factors, this delay to 1 October appears the sensible decision for all market stakeholders. The move has been broadly welcomed by market participants who view this additional period as a necessity to resolve ongoing central market operator system issues and to facilitate a seamless transition to I-SEM.

    This new date will impact both suppliers and generators to varying degrees. In the short term, there is the issue of capacity market clarity and the I-SEM DC and NDC CFDs sold to suppliers. These CFDs will be reissued with the old SEM pricing formulae (which suits suppliers with summer gas at 50 p/therm), these will also be marked against the SMP as opposed to the day ahead hourly auction. The SEM-GB interconnector capacity will now continue to be sold as physical transmission rights (PTRs) for this four month window as opposed to the envisioned financial transmission right (FTR) market. In the longer term, a drawback of the proposed new go-live date is that it corresponds with the onset of winter and associated pricing volatility. A May start with low demand and relatively pleasant weather would have provided participants with a gentle transition to this new traded market.

    If you have any questions in relation to I-SEM or the trading services offered by Erova Energy, feel free to contact us at trading@erovaenergy.ie